The original is unclear.
Another path is available.
A check is unresolved and ACH is proposed, or an API times out and a bank portal is available. What could still pay?
Discuss this exceptionOptional workflow review
The original is unresolved. Another path is available. What should your team do next?
Bring one payment exception or a planned fallback. Get a document review of supplied records and a written next action.
Paid document review. Scope and fees are agreed before work begins. Start with the payment owner; no engineering preparation is needed for this review.
Start with the free Workspace Sandbox. SDK fixtures, local evaluation and installed runtime checks have separate setup and evidence scopes. Optional assistance is separately agreed. See current pricing and qualification.
Fictional document-review sample
The next question
What couldWhat you receive
Four written outputs.
One agreed workflow.
Link the original payment, proposed replacement and what was known when the decision was made.
Show the agreed payment paths, current controls and decision owners. Excluded paths stay explicit.
Identify what supports a decision and what is still missing. Missing evidence stays inconclusive.
Keep a control, define a repair or request more evidence. Name the owner and the conditions for the next step.
Scope, deliverables, timing, effort cap, fees, access and retention are agreed before paid work. Document review and technical testing have separate scopes. Preparation and testing are quoted separately.
Start with the payment owner. No engineering preparation is needed for the first conversation. Document review does not verify execution safety or authorize a payment. Review and testing conditions.
Start with a real decision
A recent exception or an upcoming change is enough to begin. Share the question, then agree the work.
A check is unresolved and ACH is proposed, or an API times out and a bank portal is available. What could still pay?
Discuss this exceptionReview which controls and evidence the alternative path needs before your team relies on it.
Discuss this changeClarify who decides, what each person knows and which independent actions can still release money.
Discuss the handoffDocument-review sample
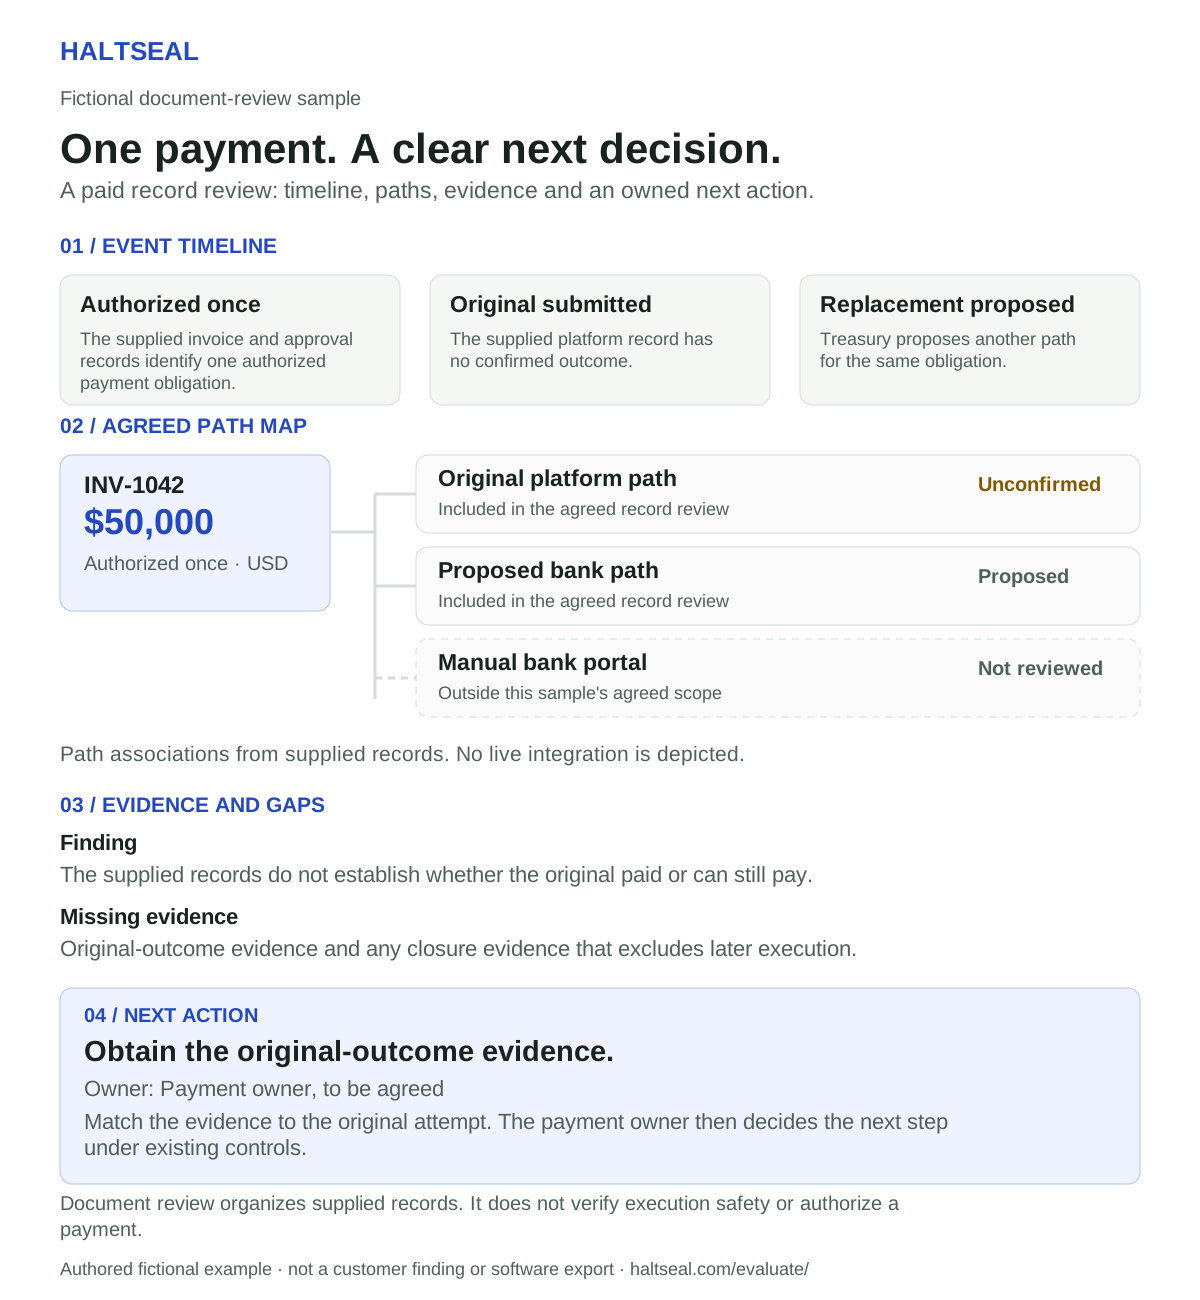
A fictional unresolved payment, its agreed paths, the evidence gap and a next action. The review uses supplied records; technical testing is a separate engagement.
Fictional document-review sample
$50,000INV-1042 · USD
The supplied invoice and approval records identify one authorized payment obligation.
The supplied platform record has no confirmed outcome.
Treasury proposes another path for the same obligation.
Same obligation: INV-1042
Included in the agreed record review
Included in the agreed record review
Outside this sample's agreed scope
Connections show paths associated with the supplied records. They do not show a live integration or an enforced release boundary.
Document review organizes supplied records. It does not verify execution safety or authorize a payment. This is an authored example, not a customer finding or a software-exported report.
Open the shareable review diagram · SVGScope and team effort
Your proposal confirms the scope, fee and delivery date. We then arrange how to share the records needed for your review.
Paid work begins after you and HALTSEAL Inc. accept a separate written agreement.
Document review
A payment owner and permitted records are enough to scope a document-based review. We organize the timeline, paths, current controls and evidence gaps. No engineer or test environment is required for this phase. It does not verify execution safety.
Separate technical testing
Agree engineering participation, approved access, scenarios and preparation separately. Testing begins in an accepted non-production environment with independently controlled measures to prevent real funds from moving. Findings apply to the executed scope.
A concise engagement overview for your Controller, Treasurer or payment owner. No login or email required.
Separate technical-test sample
Illustrative technical-test readout: workflow finding, execution readiness and a next proof with an owner. Testing is separately scoped from document review.
Manual portals, other providers and production conditions are outside this example.
The fallback stays on hold while the original is unresolved. Authoritative no-effect evidence enables a fresh review.
Retain the control and its evidence.
Retest when a provider or retry rule changes.
KEEP concerns the existing control in this illustration. It does not qualify HALTSEAL to govern a live payment.
Readout format follows v1.1.0. Fictional illustration, not a software export or customer finding. Unassigned owners and unagreed dates remain open.
Illustrative Assessment Readout / 01
Synthetic exampleNo customer system or real provider was evaluated for this sample.
Can we retain the existing fallback control within this scope?
Illustrative conclusion
Equivalent findings in an accepted exercise could support retaining the existing control within the tested scope.
The square represents a payment request. HOLD describes that request, not the Assessment conclusion.
ILL references identify this illustration, not test traces.
ILL-01In this illustrative sequence, the existing control holds the fallback while the original outcome is unresolved.
ILL-02A real finding requires source records across the agreed tested cases.
ILL-03Authoritative no-effect evidence may restore eligibility. A fresh exact release request still needs current authority.
ILL-04The illustration covers the primary and fallback decision sequence. Excluded routes remain outside the findings.
KEEP concerns the existing control in this illustration. It does not qualify HALTSEAL to govern a live payment.
Readout format follows v1.1.0. Fictional illustration, not a software export or customer finding. Unassigned owners and unagreed dates remain open.
What the findings mean
Retain what the agreed review supports. Tested conclusions apply only to the paths exercised. Reassess when the workflow changes.
Repair the control or restrict the path. Retest before relying on the change.
Missing evidence stays inconclusive. It never becomes a pass.
Existing controls may pass without installing HALTSEAL. Incomplete evidence stays inconclusive.
Q04b · recorded local case · synthetic. Fallback admission lacked required closure evidence. One payment observed; admission control: FAIL. No customer system or real funds.
A gap may support an internal fix or a restricted path.
Inspect the case and its limitsCurrent evidence: Qualification Kit v1.1.0 is offline, local and synthetic. Customer test findings require an accepted test setup. Evidence and limits.
How to start
A recent unresolved payment or a planned provider, retry or fallback change.
Written scope, deliverables, timing, effort cap and fees before paid work.
Receive the agreed record, its evidence and limits, and a written next action with an owner.
Start with a payment owner. No engineering preparation is needed for the first conversation.
For document review, agree the permitted records, payment owner and review limits. Confirm the scope, fee, delivery date and customer participation in a written proposal. Additional work requires agreement.
Testing uses an agreed non-production environment with independently controlled measures that prevent real funds from moving.
Scenarios, assessment tooling, supporting records and a review of the findings.
A payment owner, an engineer, and a budget owner. Budget approval and approved test access.
Before paid work, agree scope, deliverables, timing, effort cap, fees, access and retention. Readiness preparation and test execution are quoted separately, including deliverables and fees if preparation stops.
Test execution starts only after readiness is accepted. Your review includes Authority / Safety / Recovery / Coverage findings, supporting records, exclusions and a next decision.
Map the original and fallback paths, current approvals and outcome evidence. Declare provider substitutions and excluded manual actions. Exercise the agreed uncertainty, retry, authority-change and recovery conditions. Missing evidence stays inconclusive.
Reassess a new provider or fallback path, revised mapping, or changed approval, retry or recovery rules. Agree scope, preparation and fees separately, and accept test readiness before execution.
Map your paths with the coverage worksheet or review the manual bank payment guide. Excluded manual actions remain outside the automated findings.
HALTSEAL installation is not required. Optional offline Shadow has no payment authority; live capture needs a reviewed integration. Additional execution control is a separate evaluation requiring technical validation and customer approval. Integration conditions.
Review a workflow
A short note is enough to start.
Email and a non-confidential note. Name and company are optional.
Discuss scope and fees20 minutes with Scott Lee, founder.